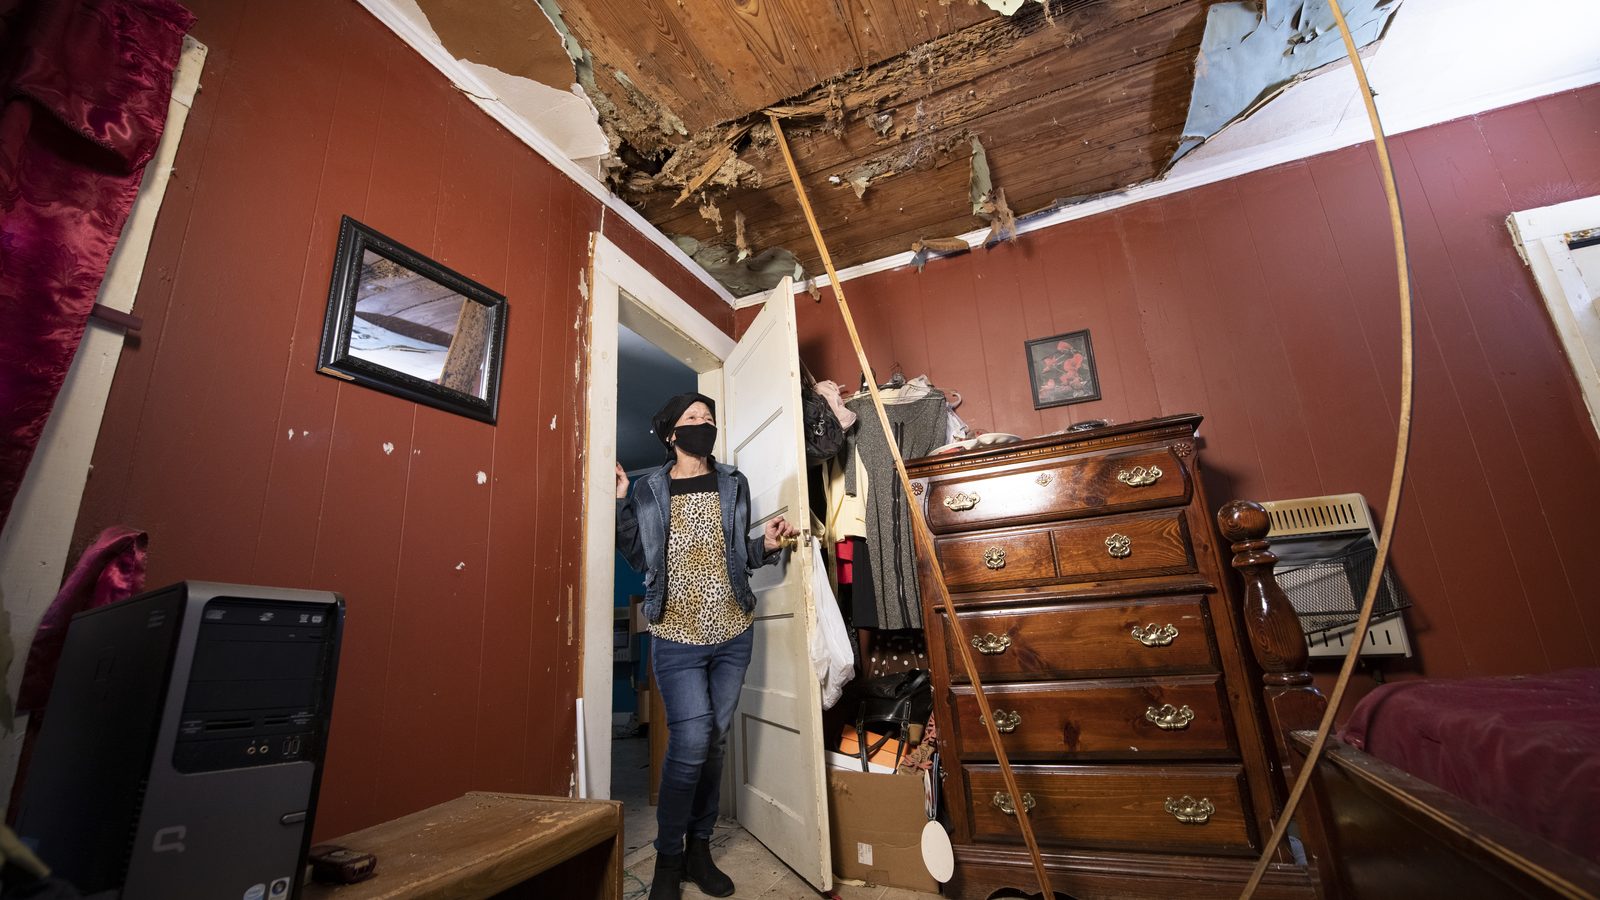
If your Texas roof claim is denied or underpaid, start by getting the reason in writing and comparing it with the damage documentation. A roofing contractor can re-inspect and give you photos, measurements and a revised estimate so you can ask your insurer to review missed items. Disputes over coverage or the amount belong with you, a licensed public adjuster, an attorney or TDI.
A denial letter feels final. Often it is not. Some denials are correct: the damage really is wear, or the repair really costs less than the deductible. Others come from an inspection that missed a slope, a scope that left out required items, or a disagreement about what caused the damage. Knowing which situation you are in decides your next step. Here is how we approach it as a roofing contractor, including the lines Texas law says we cannot cross.
Why do roof claims get denied or underpaid in Texas?
The Texas Department of Insurance lists the common reasons in why a home insurance claim might be denied or not paid. The ones we see most on roofs:
Common reasons roof claims are denied or underpaid
| Reason | What it means | Denial or underpayment |
|---|---|---|
| The damage is below the deductible | The insurer may close the claim without payment. | Denial |
| The insurer attributes the damage to wear, age or installation | TDI notes insurers won't pay for a new roof just because it's old. | Denial |
| A policy exclusion applies | For example, a cosmetic damage exclusion or a roof endorsement. | Denial |
| The scope is incomplete | The claim is approved, but the estimate leaves out items the job actually needs. | Underpayment |
| Depreciation | On actual cash value coverage, the payment is reduced for the roof's age. | Underpayment |
The last two are underpayment, not denial, and they are the most common reason homeowners call us after a claim.
What should I do first when my roof claim is denied?
- Get the reason in writing. Texas requires an insurer that rejects a claim to tell you why in writing.
- Read the policy language it cites. Look up the exact exclusion or condition named in the letter.
- Compare the adjuster's estimate with your evidence. Line by line: slopes inspected, measurements, items included.
- Note the deadlines. Your policy and the letter may set time limits for disputes or suits. Write them down.
- Decide what kind of problem it is. Missing evidence or missing items is a documentation problem. A disagreement about coverage or cause is a dispute.
What can a roofing contractor do after a denial, and what can't it do?
Texas draws this line clearly. A contractor may not act as a public adjuster or advertise adjusting services for property it is working on, as TDI explains in Roofing and insurance: know the law.
| A contractor can | A contractor cannot |
|---|---|
| Re-inspect and photograph every slope | Negotiate your settlement |
| Measure the roof and write an itemized scope | Interpret your policy or argue coverage for you |
| Explain technical issues such as code items or discontinued shingles | Act as your public adjuster |
| Provide documentation of missed items for you to send to your insurer | Promise a denial will be reversed |
| Attend a re-inspection if you ask | Waive, rebate or absorb your deductible (Chapter 707) |
When a claim is underpaid because items were missed, the normal step is to ask your insurer to review the missed items: we photograph and measure the missing work and give you updated photos and a revised contractor estimate to send with your request. We don't negotiate the claim. The insurer still decides.
What is the appraisal clause, and when is it used?
Most Texas homeowners policies include an appraisal provision. TDI describes it as a process for disputes about the amount of your claim. You and the insurer each hire an appraiser, the two appraisers choose an umpire, and the umpire's decision is binding on both sides. You pay your own appraiser and half of the umpire's expenses.
Appraisal can be useful when both sides agree there is covered damage but disagree on the cost. It generally is not the tool for a disagreement over whether damage is covered at all. Read your policy's appraisal clause, and consider getting advice before invoking it, because the result is binding. TDI's same page also describes mediation as another option.
When should I call a public adjuster, an attorney or TDI?
| Who | What they do |
|---|---|
| A licensed public adjuster | Represents you, not the insurer, for a fee. TDI notes fees can be up to 10% of what the insurer pays, and public adjusters must be licensed by TDI. |
| An attorney | Can advise on coverage disputes and your legal options. Texas has specific pre-suit notice rules for weather-related property claims in Insurance Code Chapter 542A, one reason to get advice early rather than late. |
| TDI | Accepts homeowners insurance complaints and can review whether an insurer followed the law and your policy. The help line is 800-252-3439. TDI cannot make a company pay unless the failure to pay breaks a law or your policy terms. |
How do I avoid a weak claim in the first place?
Most disputes we see trace back to thin evidence. Document before you file, be present for the inspection, and make sure every slope is looked at. Our guide to how roof claims work in Texas covers the full process, and our claim documentation page shows what a complete file looks like. If a contractor promises to "get your claim approved" or offers to handle your appeal, walk away; that is not a contractor's job in Texas.
Denied and underpaid claim questions
Can I reopen a roof claim that was denied?
Ask your insurer. Many will reconsider when you provide new information, such as documentation of damage the first inspection missed. Watch the deadlines in your policy and the denial letter, and get advice if a large amount is at stake.
Is a supplement the same as an appeal?
No. A supplement asks the insurer to review specific items that were left out of an approved scope, backed by photos and measurements. An appeal or dispute challenges the insurer's coverage decision, which is for you, a public adjuster or an attorney.
Will Storm Bolt Roofing talk to my insurer about the denial?
We can share our photos, measurements and estimate, and answer technical roofing questions. We cannot negotiate, argue coverage or represent you. For that, talk with a licensed public adjuster or an attorney, or call TDI.
Not sure whether your denial is a documentation gap or a real dispute? Book a free, photo-documented re-inspection or call Storm Bolt Roofing at 832-860-0262, and we will tell you plainly what the roof shows.