
Roof Insurance Claim Documentation for Houston Homeowners
The adjuster is coming and the roof is the biggest line on your claim. Our job is the evidence: drone photos, measurements, and an itemized contractor scope — ready before the adjuster's inspection.
Live near our Spring home base? Our Spring insurance claim documentation page speaks to those neighborhoods directly.
From First Photo to Final Closeout
Climb & capture
Every slope gets drone and ladder photos — hail bruising, creased tabs, lifted shingles — organized so an insurer can follow them. Here is how to document roof damage for insurance on your side.
Measure & itemize
Roof measurements feed a line-by-line written scope your carrier can set next to its own adjuster's numbers.
Explain it
When the adjuster inspects your roof, our findings are already on paper. At your request, we can be there to answer construction questions; the claim itself stays between you and your insurer. Here is what happens at an adjuster inspection.
Rebuild & close out
After approval we install the roof, photograph the finished work, and hand over the closeout file carriers look for before releasing held-back funds.
A Contractor's Role, Marked Plainly
✓ Ours to do
Photograph and measure the damage · write the itemized scope · be present, at your request, when your adjuster inspects the roof · build the approved roof and warranty the workmanship.
✗ Never ours
Adjusting or negotiating your claim · predicting what your carrier will pay · promising approval · touching your deductible in any way.
Hail Overnight? Wind Still Ringing?
Get the roof documented before a small opening becomes a ceiling stain. The inspection is free, and every photo is yours to keep.
Put Your Roof's Evidence on Paper
Describe the storm — hail, wind, when the water showed up inside. We'll walk the roof, photograph every slope, and write the scope for your claim file. Whether to file, and what to accept, is always your decision.
Photo Report
Drone and ladder shots, organized slope by slope.
Itemized Scope
Line-by-line pricing an insurer can actually compare.
Straight Answer
If the damage doesn't justify a claim, we say so.
Two Languages
The whole process in English or Spanish.
Book a Documented Roof Inspection
Free of charge. We reply on business days to set a time.
The Language on Your Claim Paperwork
Four terms decide how a Houston hail or wind claim actually pays out. Here they are without the jargon, from the contractor's side of the table — the claim itself always belongs to you and your insurer, never to us. For the whole sequence, from the first call to the final check, read our guide to how roof insurance claims work in Texas. For ACV, RCV and percentage wind/hail deductibles worked through with examples, see ACV vs RCV roof claims in Texas. In designated coastal areas, wind and hail can fall under a separate TWIA policy instead; most inland Houston homes are outside it (see TWIA windstorm insurance and your roof).
Your deductible
What your policy makes you pay before insurance money moves. By Texas law (Ins. Code Chapter 707) a contractor cannot waive or absorb it — anyone who offers to is a red flag.
How the deductible math works
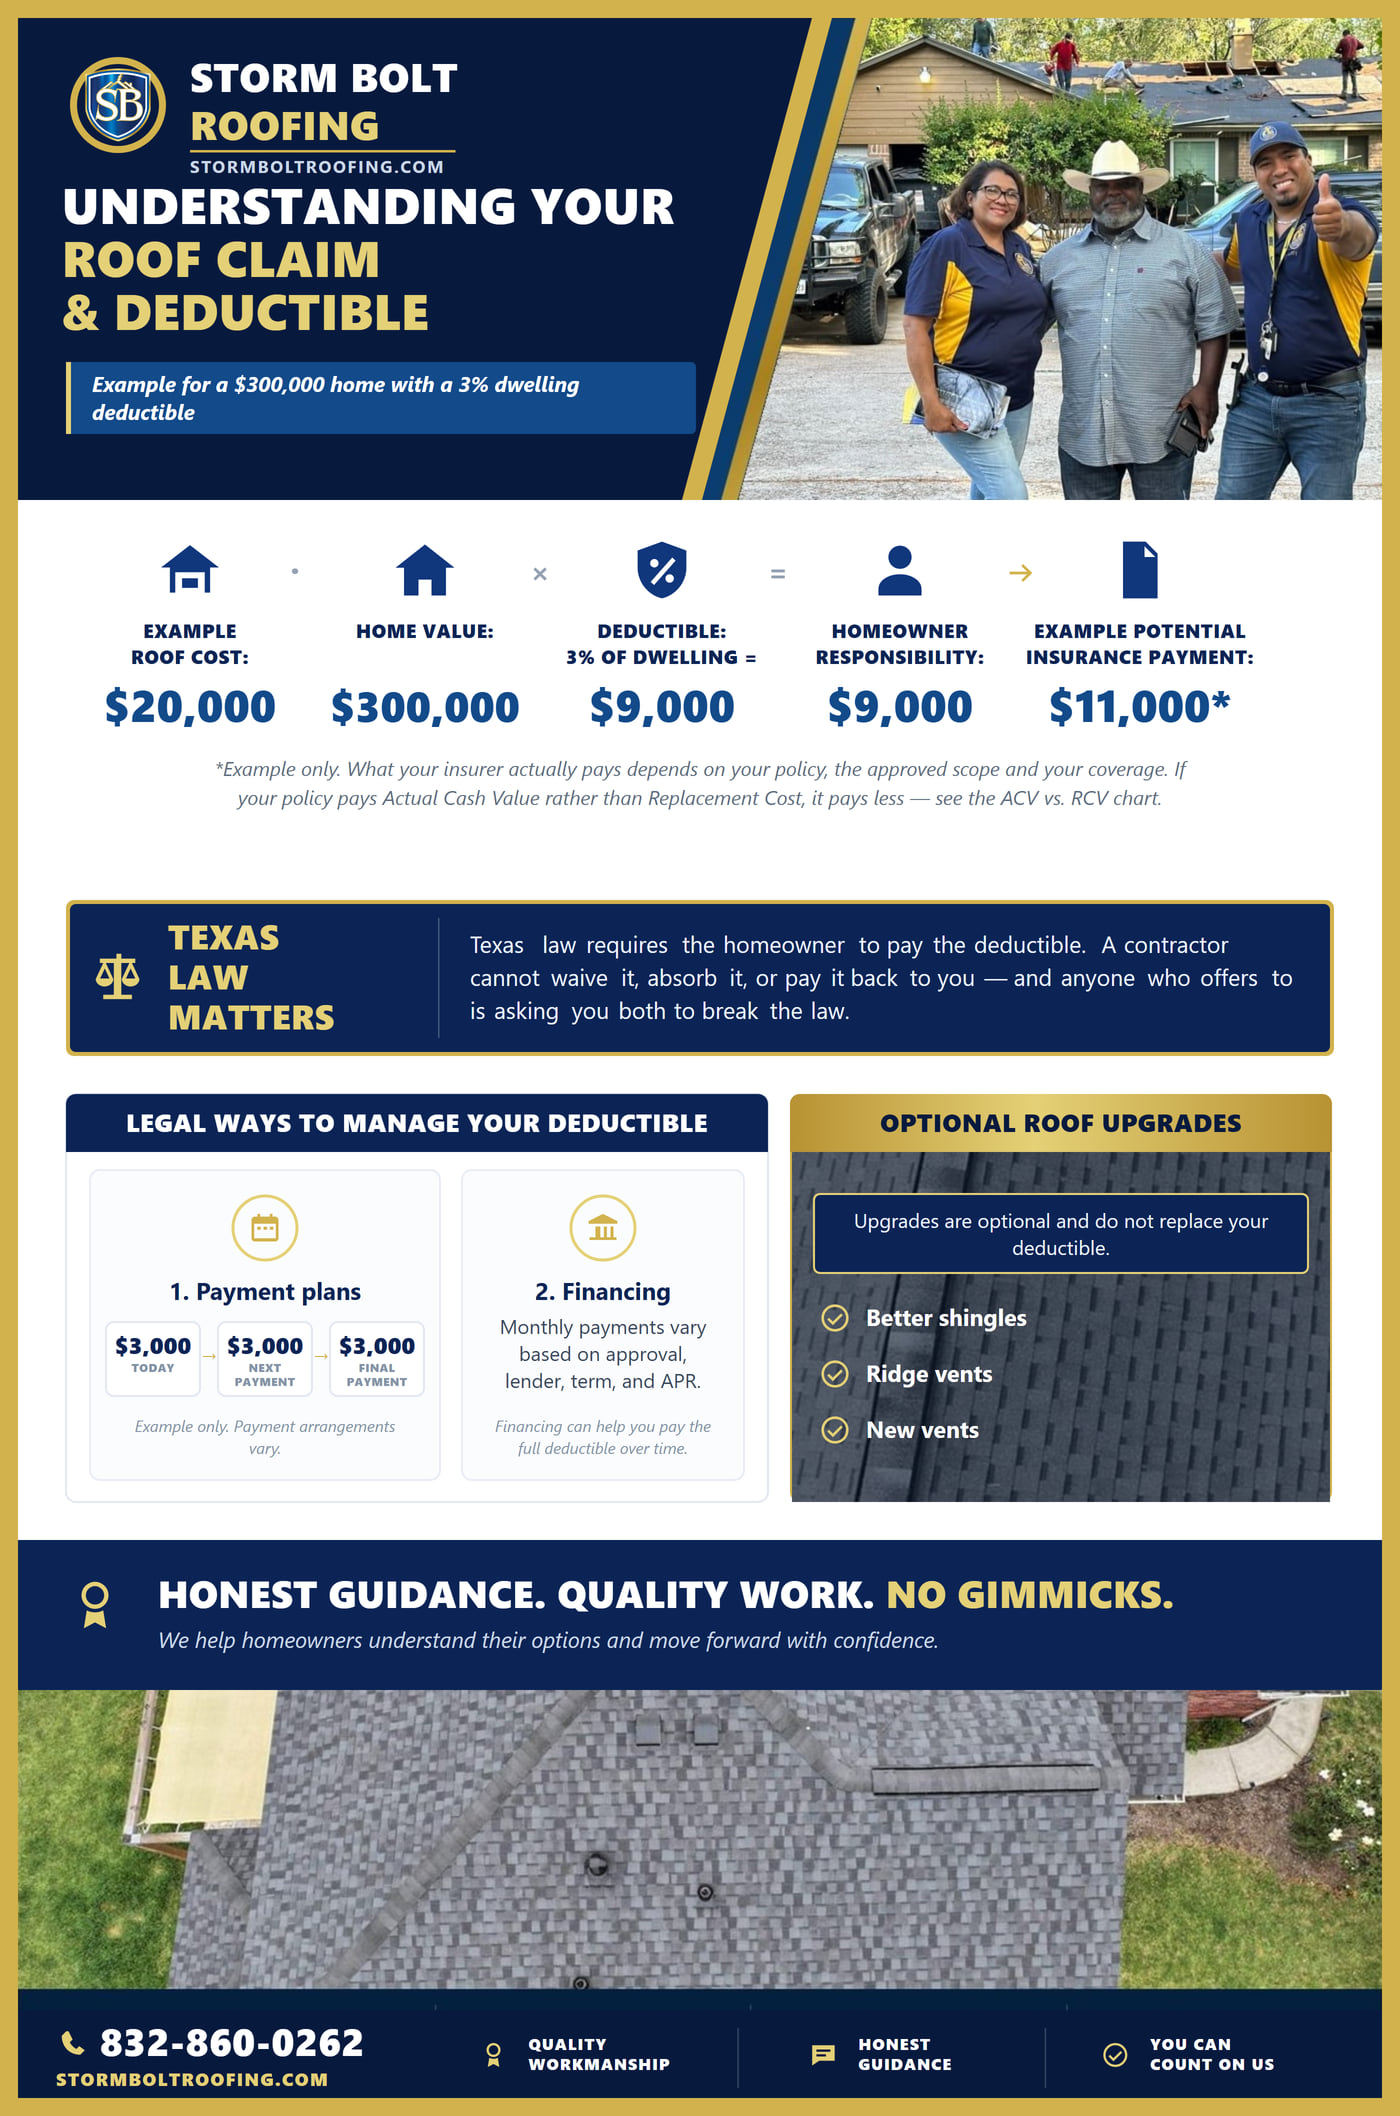
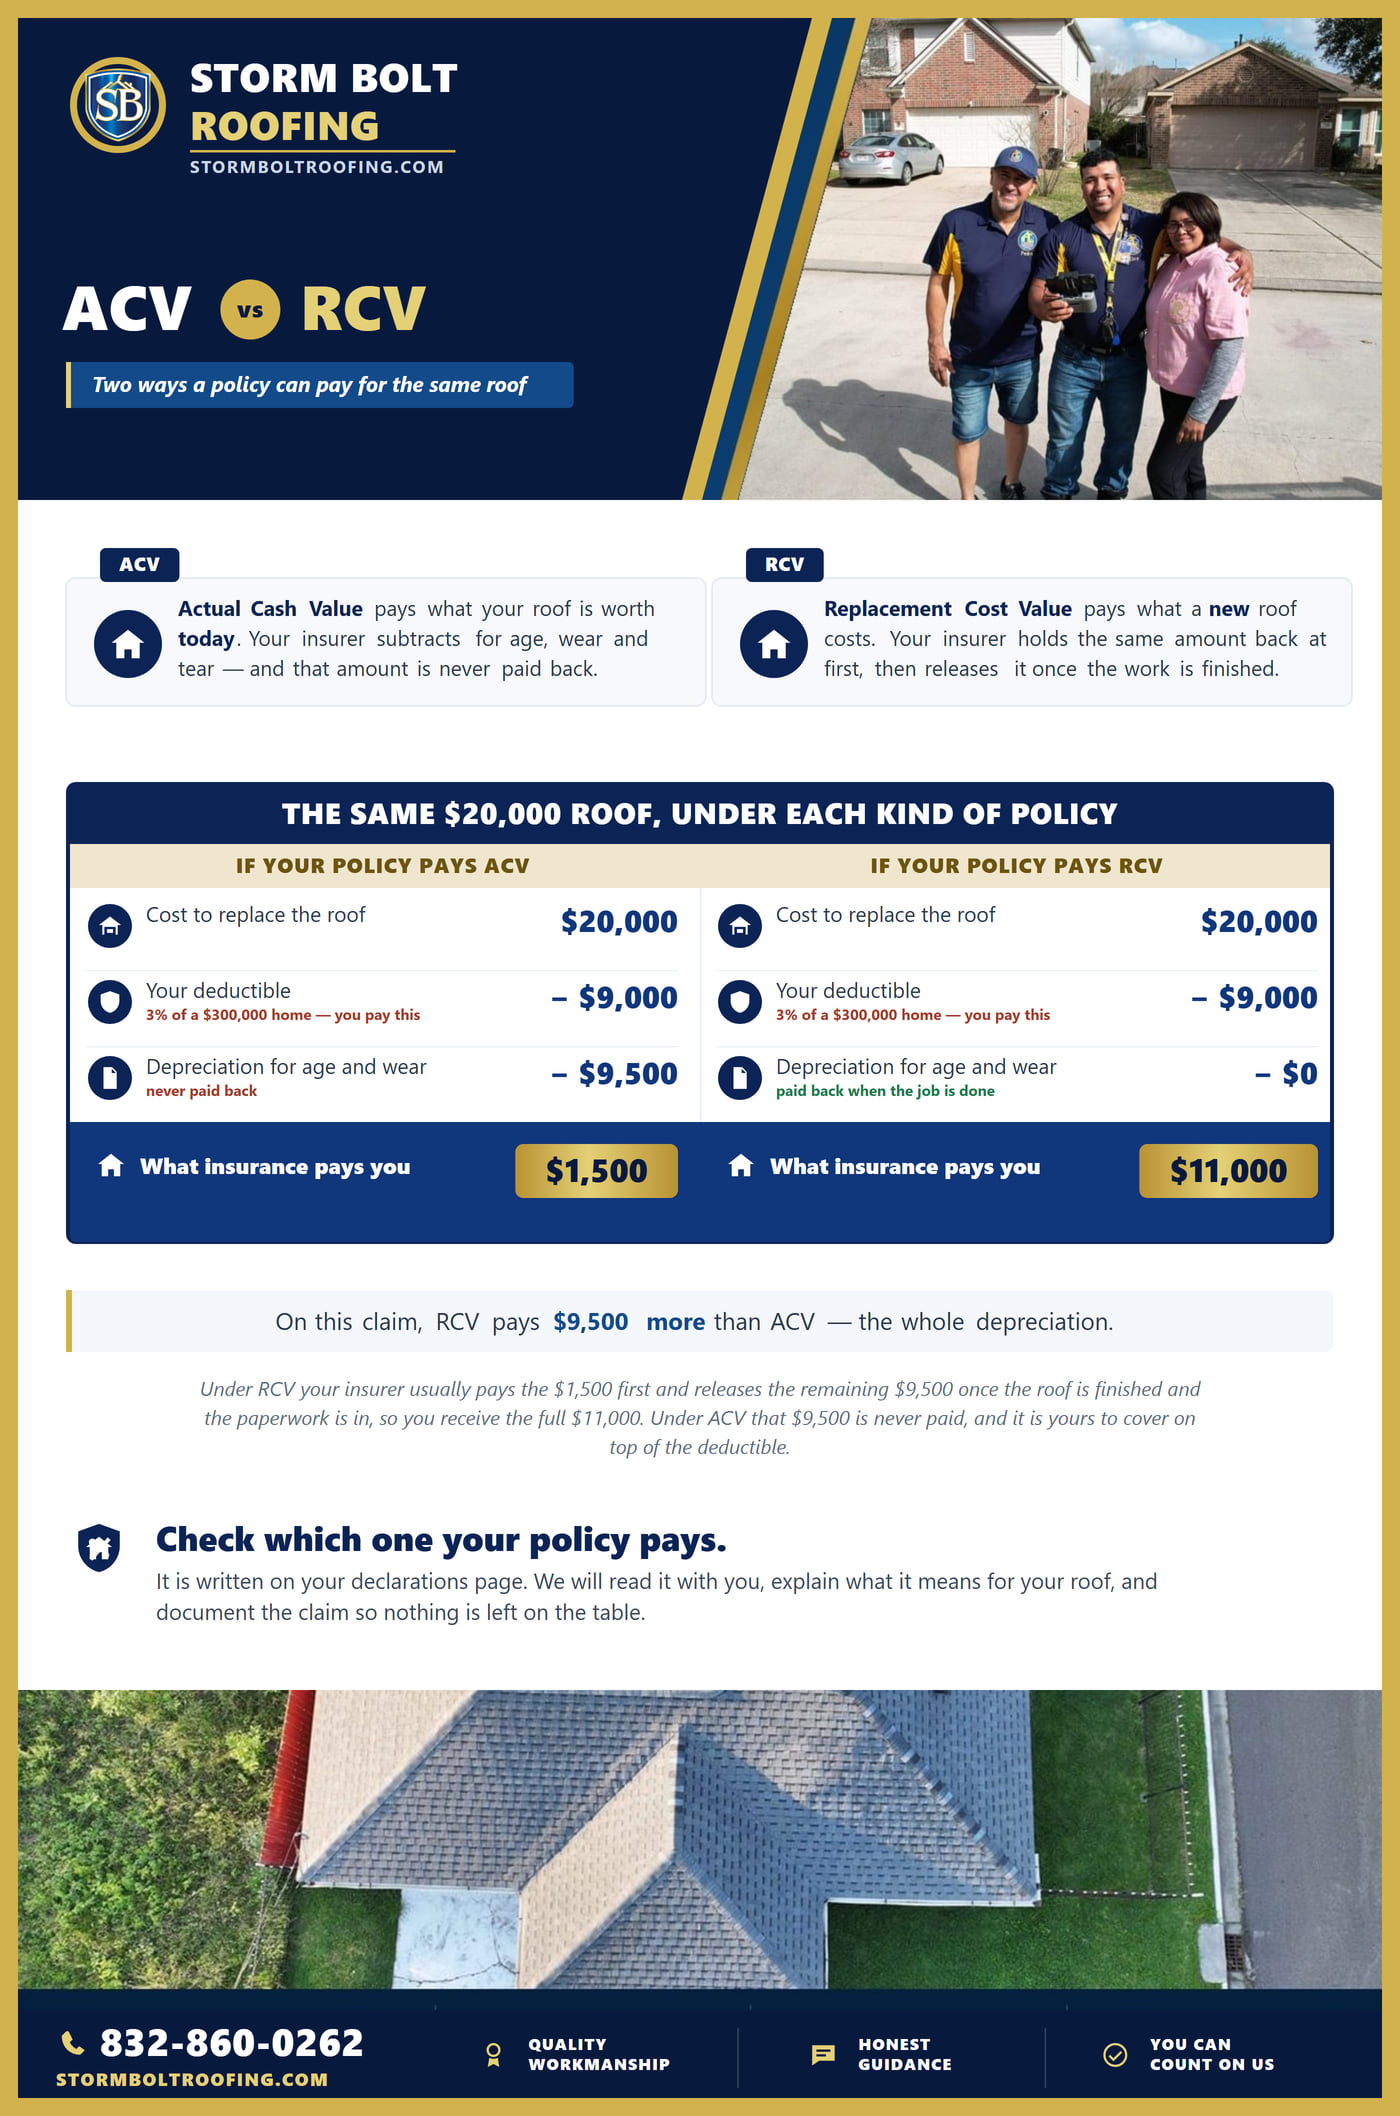
ACV vs. RCV
Two ways a policy values the same roof: depreciated (Actual Cash Value) or at today's replacement cost (RCV). RCV policies usually pay in two checks, the second after the work is finished and documented.
Compare the two on one claim
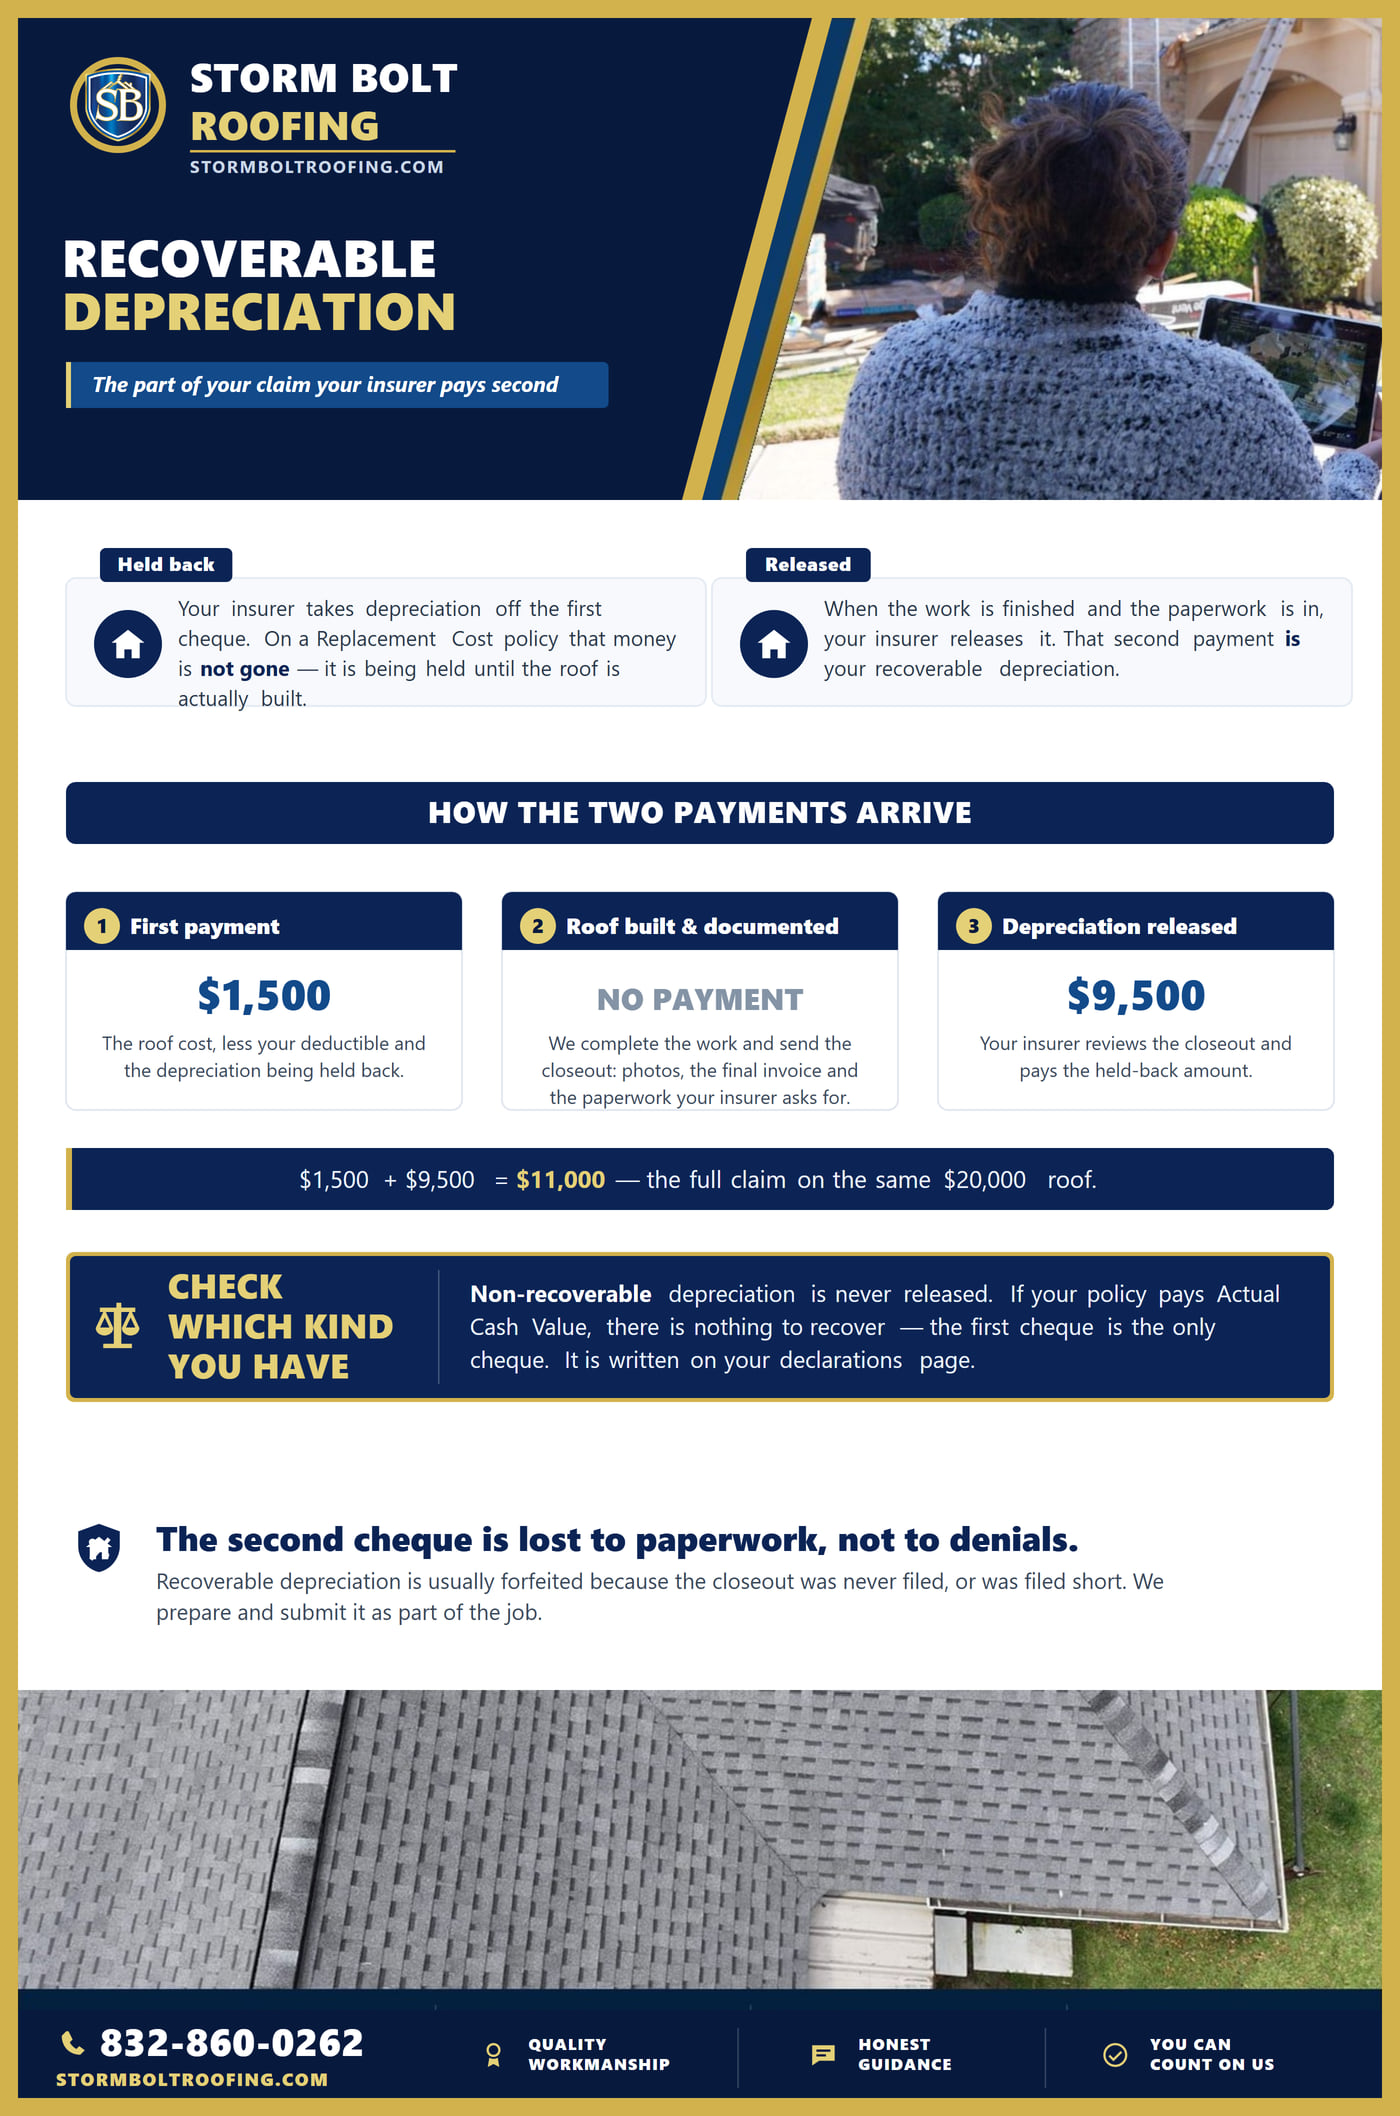
Recoverable depreciation
The held-back portion of an RCV payment. It releases when your carrier sees proof the roof was actually completed — which is exactly what our closeout file exists to show.
Where the second check comes from
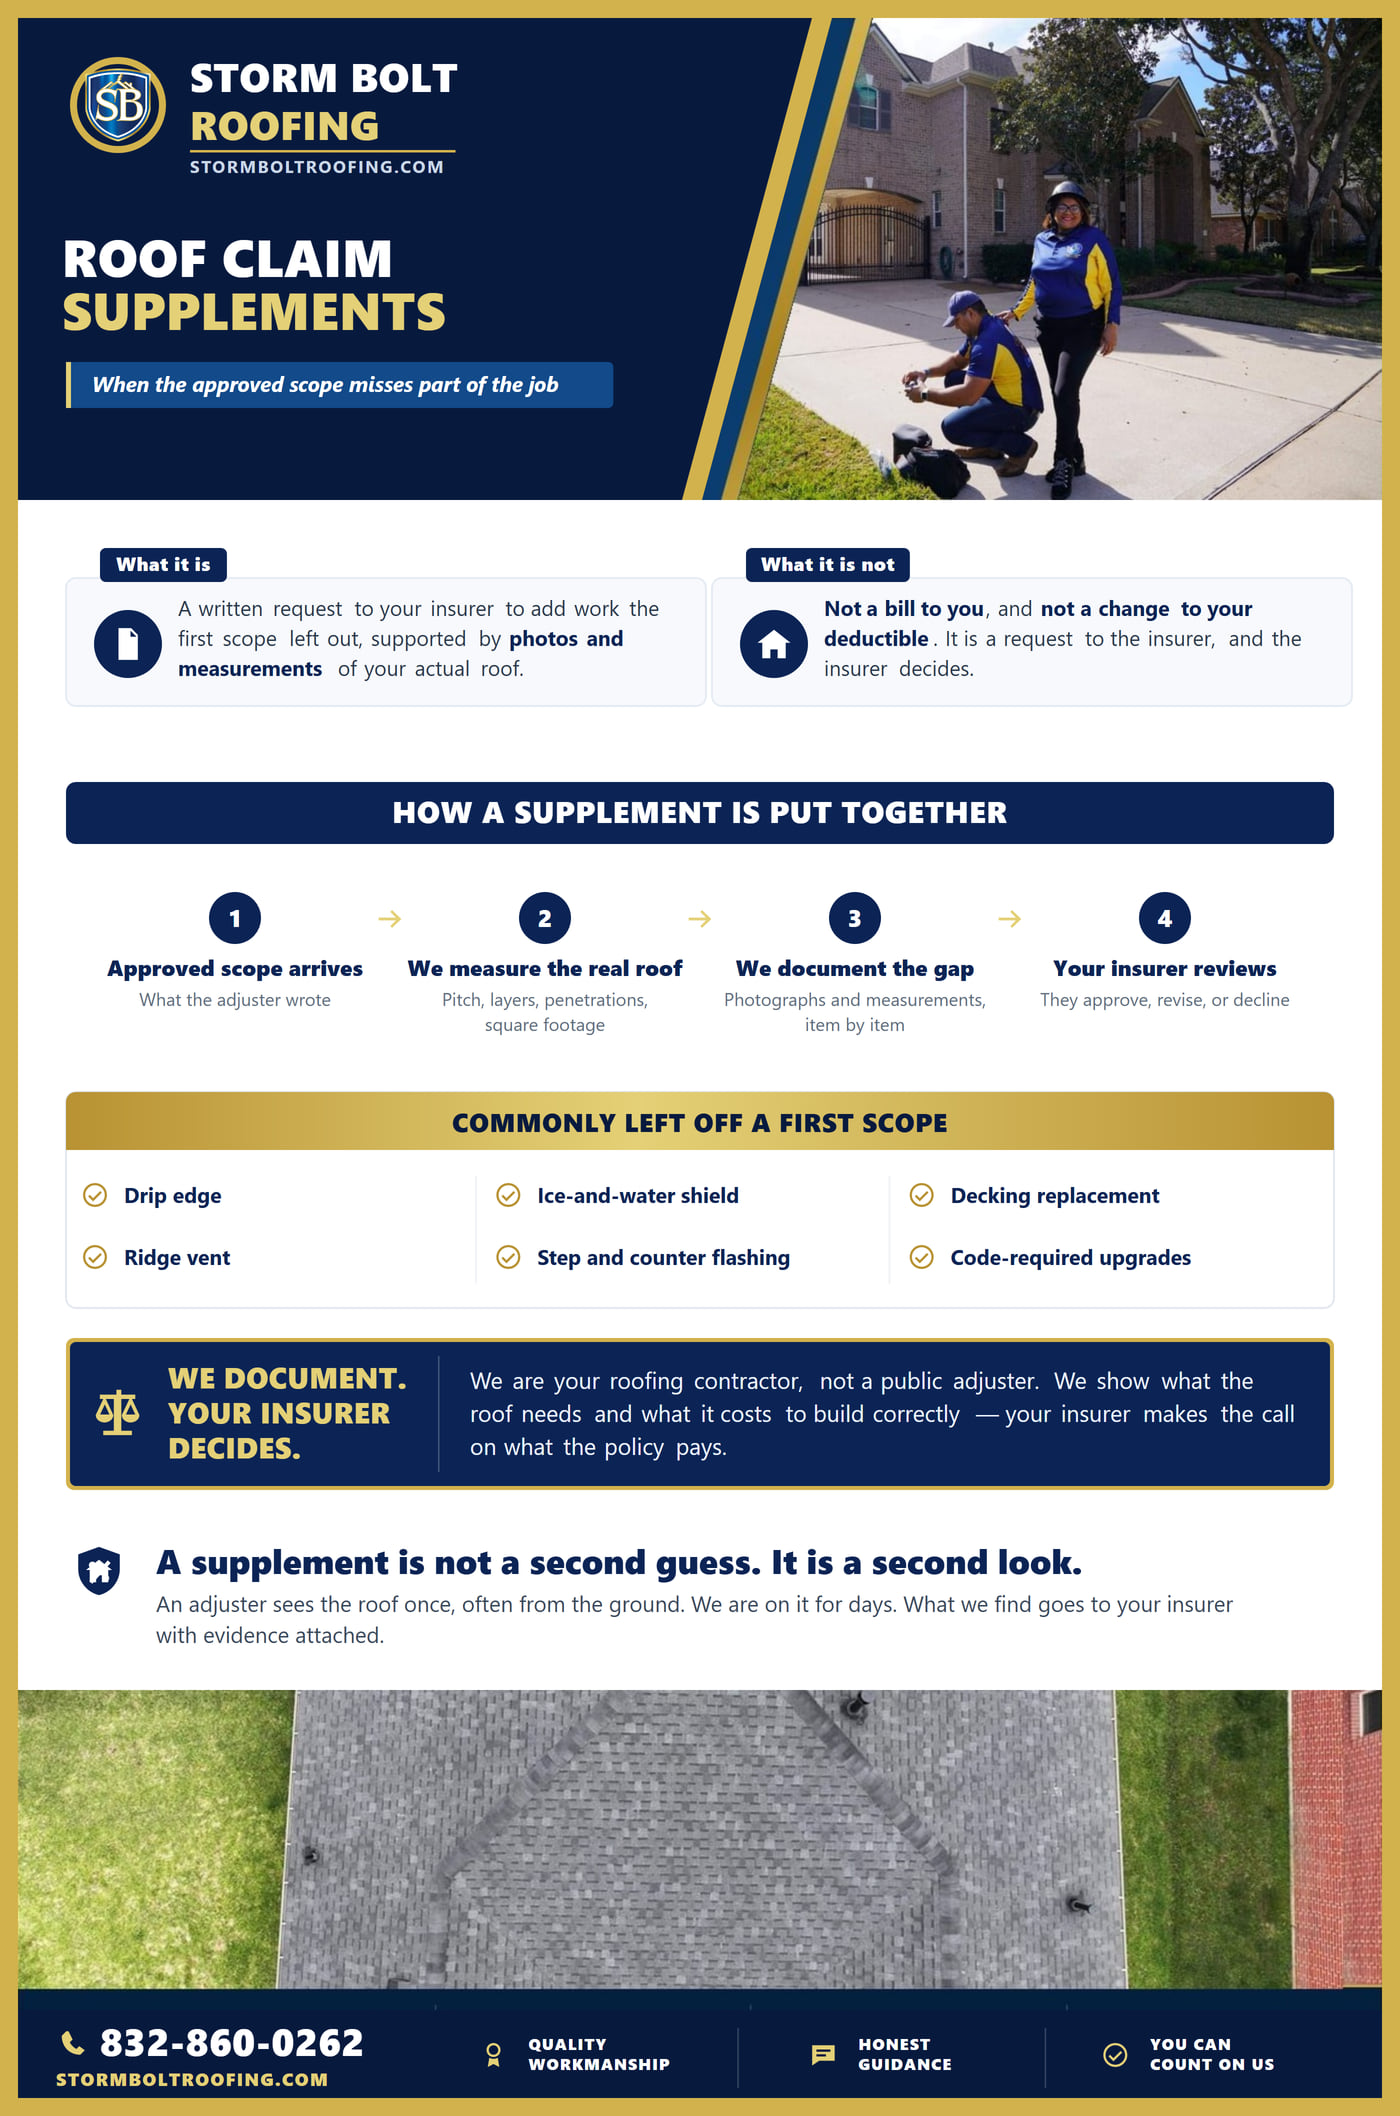
Supplements
When the first approved scope leaves out real items — drip edge, decking, code-required upgrades — we photograph and measure the gap and give you a revised estimate and the photos to send to your insurer to review.
What goes into a supplement
Where a claim goes after the storm
Evidence first
The roof gets photographed and measured before anything else; you decide whether to file with your carrier.
Adjuster inspection
Our photo report and scope are on the table when your insurer's adjuster arrives, and at your request we can be there to answer construction questions.
Scope comes back
Your carrier approves what it approves. Gaps in that scope can be documented in a supplemental estimate for your insurer to review (see how roof claim supplements work in Texas). If it comes back denied or underpaid, read your options after a denied roof claim in Texas.
Build & second check
We install the approved roof and deliver the closeout proof your carrier wants before releasing recoverable depreciation.
Claim Documentation Questions
What does your claim documentation actually include?
A slope-by-slope photo report from drone and ladder, roof measurements, an itemized written scope, and — after an approved build — closeout photos of the finished work. All of it is yours.
Do you file or negotiate the claim for me?
No. A roofing contractor is not a public adjuster, and we never act as one. You file and manage the claim with your carrier; our part is the roof and the evidence behind it.
Can you tell me whether my hail damage will be covered?
Nobody can promise that, and anyone who does is a warning sign. We can show you precisely what is on your roof; coverage is your insurer's decision under your policy. For how policies usually separate sudden storm damage from wear and tear, read does insurance cover a roof leak in Texas?
The storm was weeks ago — is it too late to document?
Hail bruising and wind creasing stay visible long after the storm, so document as soon as it's safe to get on the roof. If water is already coming in, ask about emergency tarping first.