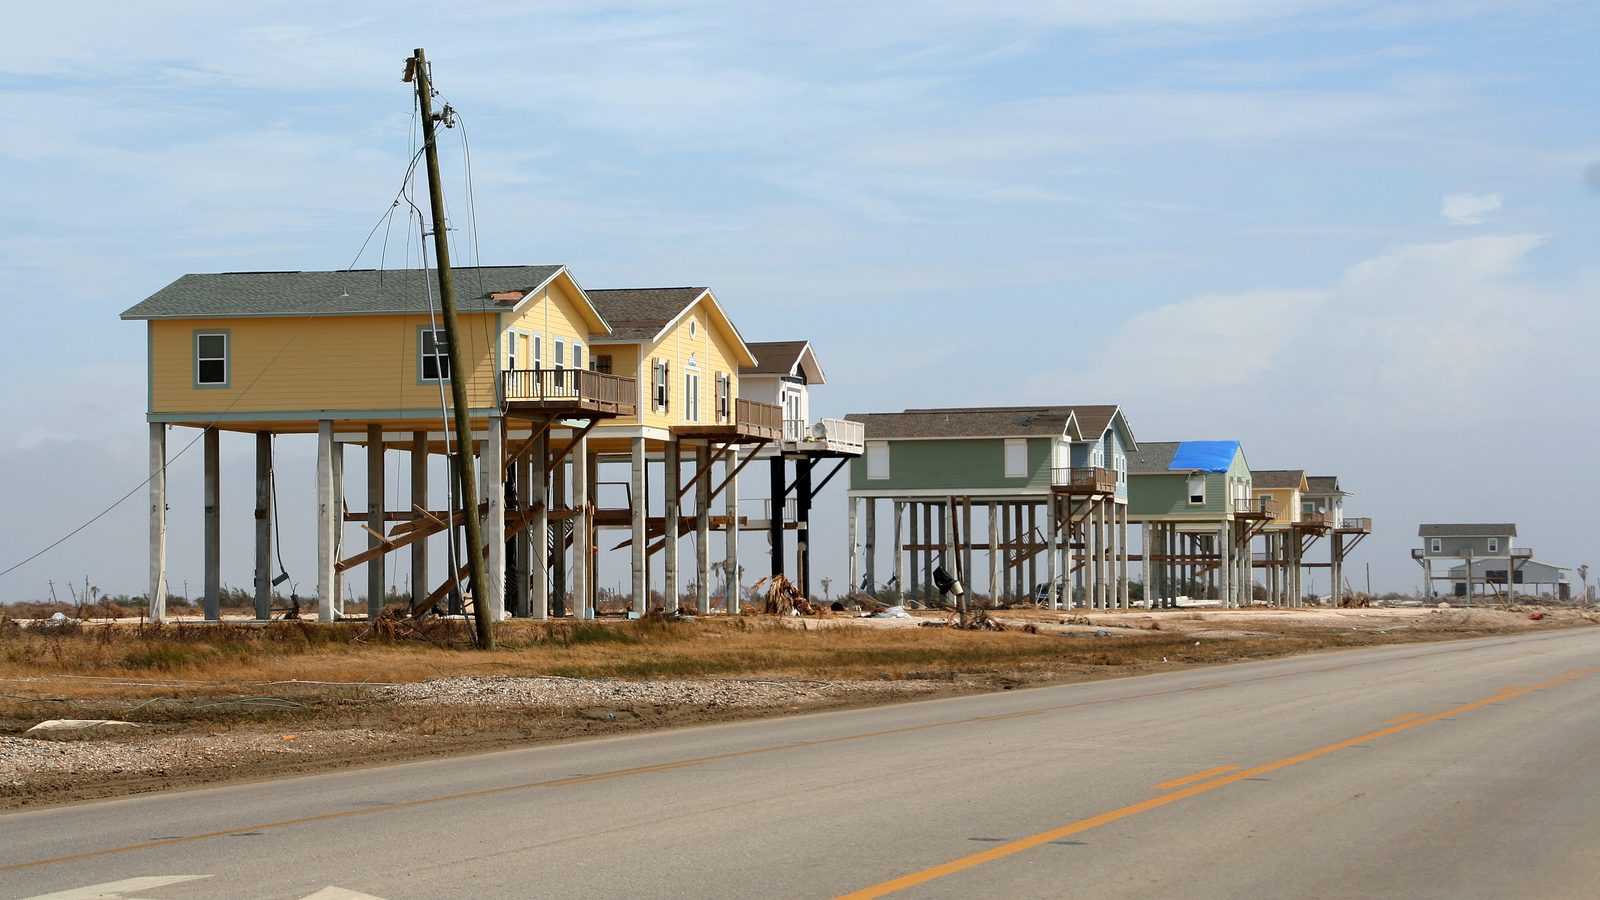
TWIA, the Texas Windstorm Insurance Association, offers wind and hail insurance to property owners on the Texas coast who cannot get that coverage in the regular market. Its designated area includes 14 first-tier coastal counties and parts of Harris County east of Highway 146, so most homes in inland Houston, Spring and the northern suburbs are outside it. Inland homeowners usually have wind and hail coverage in their homeowners policy instead. Check your own policy, and verify details with TDI or TWIA.
After a hurricane or a big windstorm, TWIA comes up in the news and in conversations with neighbors, and many Houston-area homeowners wonder whether it applies to them. For most people in Spring, Cypress, Tomball or The Woodlands, it does not. For families closer to the coast, it may be an important part of how their roof is insured. Here is what TWIA is, who it serves, how it fits with a homeowners policy and where to confirm the details for your home.
What is TWIA?
TWIA describes itself as a not-for-profit insurance company offering windstorm and hail insurance to home and commercial property owners who cannot get this coverage in the regular market due to the risk of catastrophic hurricanes. It operates under requirements set by the Texas Legislature in Texas Insurance Code Chapter 2210.
TWIA covers wind and hail only. It is not a full homeowners policy, and it is not flood insurance. Coastal homeowners who have a TWIA policy typically also have a homeowners policy for other risks, and often a separate flood policy.
Which areas of Texas does TWIA cover?
According to TWIA's coverage and eligibility page, property must be in the area designated by the Commissioner of Insurance, which currently includes all 14 first-tier coastal counties and parts of Harris County east of Highway 146:
- Coastal counties: Aransas, Brazoria, Calhoun, Cameron, Chambers, Galveston, Jefferson, Kenedy, Kleberg, Matagorda, Nueces, Refugio, San Patricio and Willacy.
- Harris County: only the parts east of Highway 146.
TWIA also lists other eligibility requirements, including that applicants must have been denied coverage by at least one authorized insurer writing wind and hail coverage in the area, that the property generally must be certified as built to applicable building codes (the WPI-8 certificates), and that the structure must be kept in insurable condition, in good repair with no unrepaired damage. Some properties in certain flood zones must also show proof of flood insurance. Designations and rules can change, so check TWIA's page for the current version.
Why is most of inland Houston and Spring outside TWIA?
Because TWIA's area is the coast. Of the Houston-area counties, Galveston, Brazoria and Chambers are on TWIA's list, and only parts of Harris County east of Highway 146 are included. Most of Harris County, including Spring, Cypress, Tomball and Katy, and neighboring Montgomery, Fort Bend and Waller counties, are not on the list.
The Texas Department of Insurance explains it this way: if you live anywhere in Texas except along the coast, you probably have wind and hail coverage in your homeowners policy, and your policy will pay for wind and hail damage much like it pays for fire, lightning or theft, although you may have a different deductible for windstorm damage. If you live along the coast, your homeowners insurance might not cover wind and hail, and you would need a separate windstorm policy, which many people get from TWIA.
If you are not sure where your property falls, ask your insurance agent. Do not assume based on a nearby ZIP code.
How is a windstorm policy different from a homeowners policy?
| Inland homeowners policy | Coastal setup with TWIA | |
|---|---|---|
| Wind and hail | Usually included, sometimes with a separate wind and hail deductible | Often excluded from the homeowners policy and covered by a separate windstorm policy |
| Fire, theft and other covered risks | Included per the policy | Covered by the homeowners policy |
| Flood | Not covered; requires separate flood insurance | Not covered by TWIA; requires separate flood insurance |
| How you buy it | From an insurer through an agent | TDI says you can buy a TWIA policy through your insurance agent |
| Building requirements | Set by the insurer's underwriting | Windstorm certification requirements for eligibility |
Every policy is different. Read your declarations page to see what is covered, what deductibles apply and whether your roof is covered at replacement cost or actual cash value.
What should coastal homeowners know about TWIA and their roof?
- Buy before storm season. TDI notes that you can't get a TWIA policy if there's a hurricane in the Gulf of Mexico, so do not wait.
- Keep windstorm certificates. TDI's windstorm inspections page explains that coastal properties must meet certain building standards to get windstorm insurance. Keep the certificate paperwork for your roof and other work.
- Ask about certification before roof work. If your home is in the designated area, ask your roofer and your agent what inspection and certification steps apply to a roof repair or replacement.
- Know your claim timelines. TDI says you have one year from the storm to file a TWIA claim, and 60 days from the date TWIA accepted your claim to dispute the amount and ask for an appraisal.
- You may have more than one claim. After a hurricane, wind damage may go to TWIA, other damage to your homeowners insurer and flood damage to your flood insurer.
Our guide to roof insurance claim deadlines in Texas covers timelines in more detail, and our after-the-hurricane guide walks through the first days after a storm.
What should inland Houston homeowners do?
- Pull out your homeowners policy and find the wind and hail section and deductible.
- Ask your agent whether your wind and hail deductible is a flat amount or a percentage of your dwelling coverage.
- Check how your roof is covered: replacement cost or actual cash value.
- Photograph your roof and home before storm season. Our hurricane season roof checklist has a full list.
Whichever policy you have, your insurer decides what is covered and what is paid. As a roofing contractor, we can inspect the roof and document its condition with photos. We are not a public adjuster and do not negotiate or handle claims.
TWIA questions
Do I need TWIA if I live in Spring or Cypress?
Most likely not. TWIA's designated area is the coastal counties plus parts of Harris County east of Highway 146. TDI says homeowners outside the coast probably have wind and hail coverage in their homeowners policy. Confirm with your agent.
Does TWIA cover flood damage?
No. TWIA offers windstorm and hail insurance. Flood damage requires a separate flood insurance policy.
Where can I check whether my property is in TWIA's area?
Start with TWIA's coverage and eligibility page and TDI's windstorm insurance page, and ask your insurance agent to confirm for your specific address.
Want your roof's condition documented before storm season? Book a free, photo-documented inspection with no obligation. Storm Bolt Roofing serves Spring and Greater Houston, in English and Spanish.